Mortgage refinancing in Krakow
I check your current agreement, compare bank offers and calculate whether moving the loan really pays off, including all the costs of the change. If it does not pay off, I say so straight.
What is mortgage refinancing?
It means moving your loan to another bank. The new bank repays the old loan and grants a new one on better terms. It most often pays off when you can get a clearly lower margin or a lower fixed-period interest rate. I set the savings against the costs of the change: if the savings are bigger, refinancing makes sense. I encourage clients to review their mortgage at least once a year.
When it is worth thinking about refinancing
Your margin is higher than in current offers
The margin affects your interest rate for many years. If banks offer a lower one today, moving the loan can lower both the instalment and the total cost.
The level of your current rate
With a fixed-period rate, it is worth comparing it with what banks offer today. Even a few dozen basis points of difference matter when a lot is left to repay.
A yearly review of your loan
Bank offers change, so I encourage you to compare your loan with the market once a year. The sooner you react, the more stays in your pocket in the following years.
Costs to consider before moving your loan
| Cost | What to watch for |
|---|---|
| Early repayment compensation | It is worth checking in your current agreement how much early repayment costs. |
| Fee at the new bank | Many banks refinance without a fee, but compare it with the margin and the extra conditions. |
| Property valuation | The new bank usually orders a valuation report. Sometimes an internal valuation is enough. |
| Mortgage | Court and notary fees for entering the new bank’s mortgage and deleting the old one. |
| Additional products | An account, a card or insurance the bank requires for a lower margin. Their cost has to be added too. |
From analysing your agreement to repaying the old loan
Analysing your current agreement
I check the margin, the reference rate, the interest rate and the fixed-rate period, the early repayment compensation and linked products.
Profitability calculation
I set the savings on the instalment and on the whole loan against the costs of the change. If refinancing does not pay off, I say so straight.
Applications to new banks
I submit applications to several banks at once and compare the decisions. You sign the agreement at the new bank yourself, but we prepare for it together, and if you need or want me there, I come with you to the signing of the loan agreement.
Repaying the old loan and changing the mortgage
The new bank repays the old loan, and you pay a lower instalment. At the end, you need to give the bank confirmation that the new mortgage has been entered in the land and mortgage register. Even later, you can contact me any time with questions or problems related to your mortgage. I also show you how to overpay it in the most cost-effective way.
Protection in case of illness or death
A mortgage is repaid over many years. That is why I talk with every client about what happens if one of the people repaying the loan becomes seriously ill or dies. Going through the protection options is part of my job, so the loan never becomes a burden for the family.
FAQ: mortgage refinancing
When does refinancing a loan pay off?↓
When the savings on instalments in the coming years clearly exceed the costs of changing banks. What matters most is the difference in margin or interest rate, including a fixed period, and how many years of repayment are left. The longer, the bigger the effect.
Does the bank check my borrowing capacity again when refinancing?↓
Yes. The new bank grants a new loan, so it checks your income, liabilities and BIK history just as for a first application.
Can I borrow more when refinancing?↓
At some banks, yes. You can choose an amount for any purpose or for a renovation, if your borrowing capacity and the value of the apartment allow it.
How much does the expert’s help cost?↓
You pay nothing for my help. I am paid by the bank where the loan is taken out. The offer is the same as if you applied at the bank yourself.
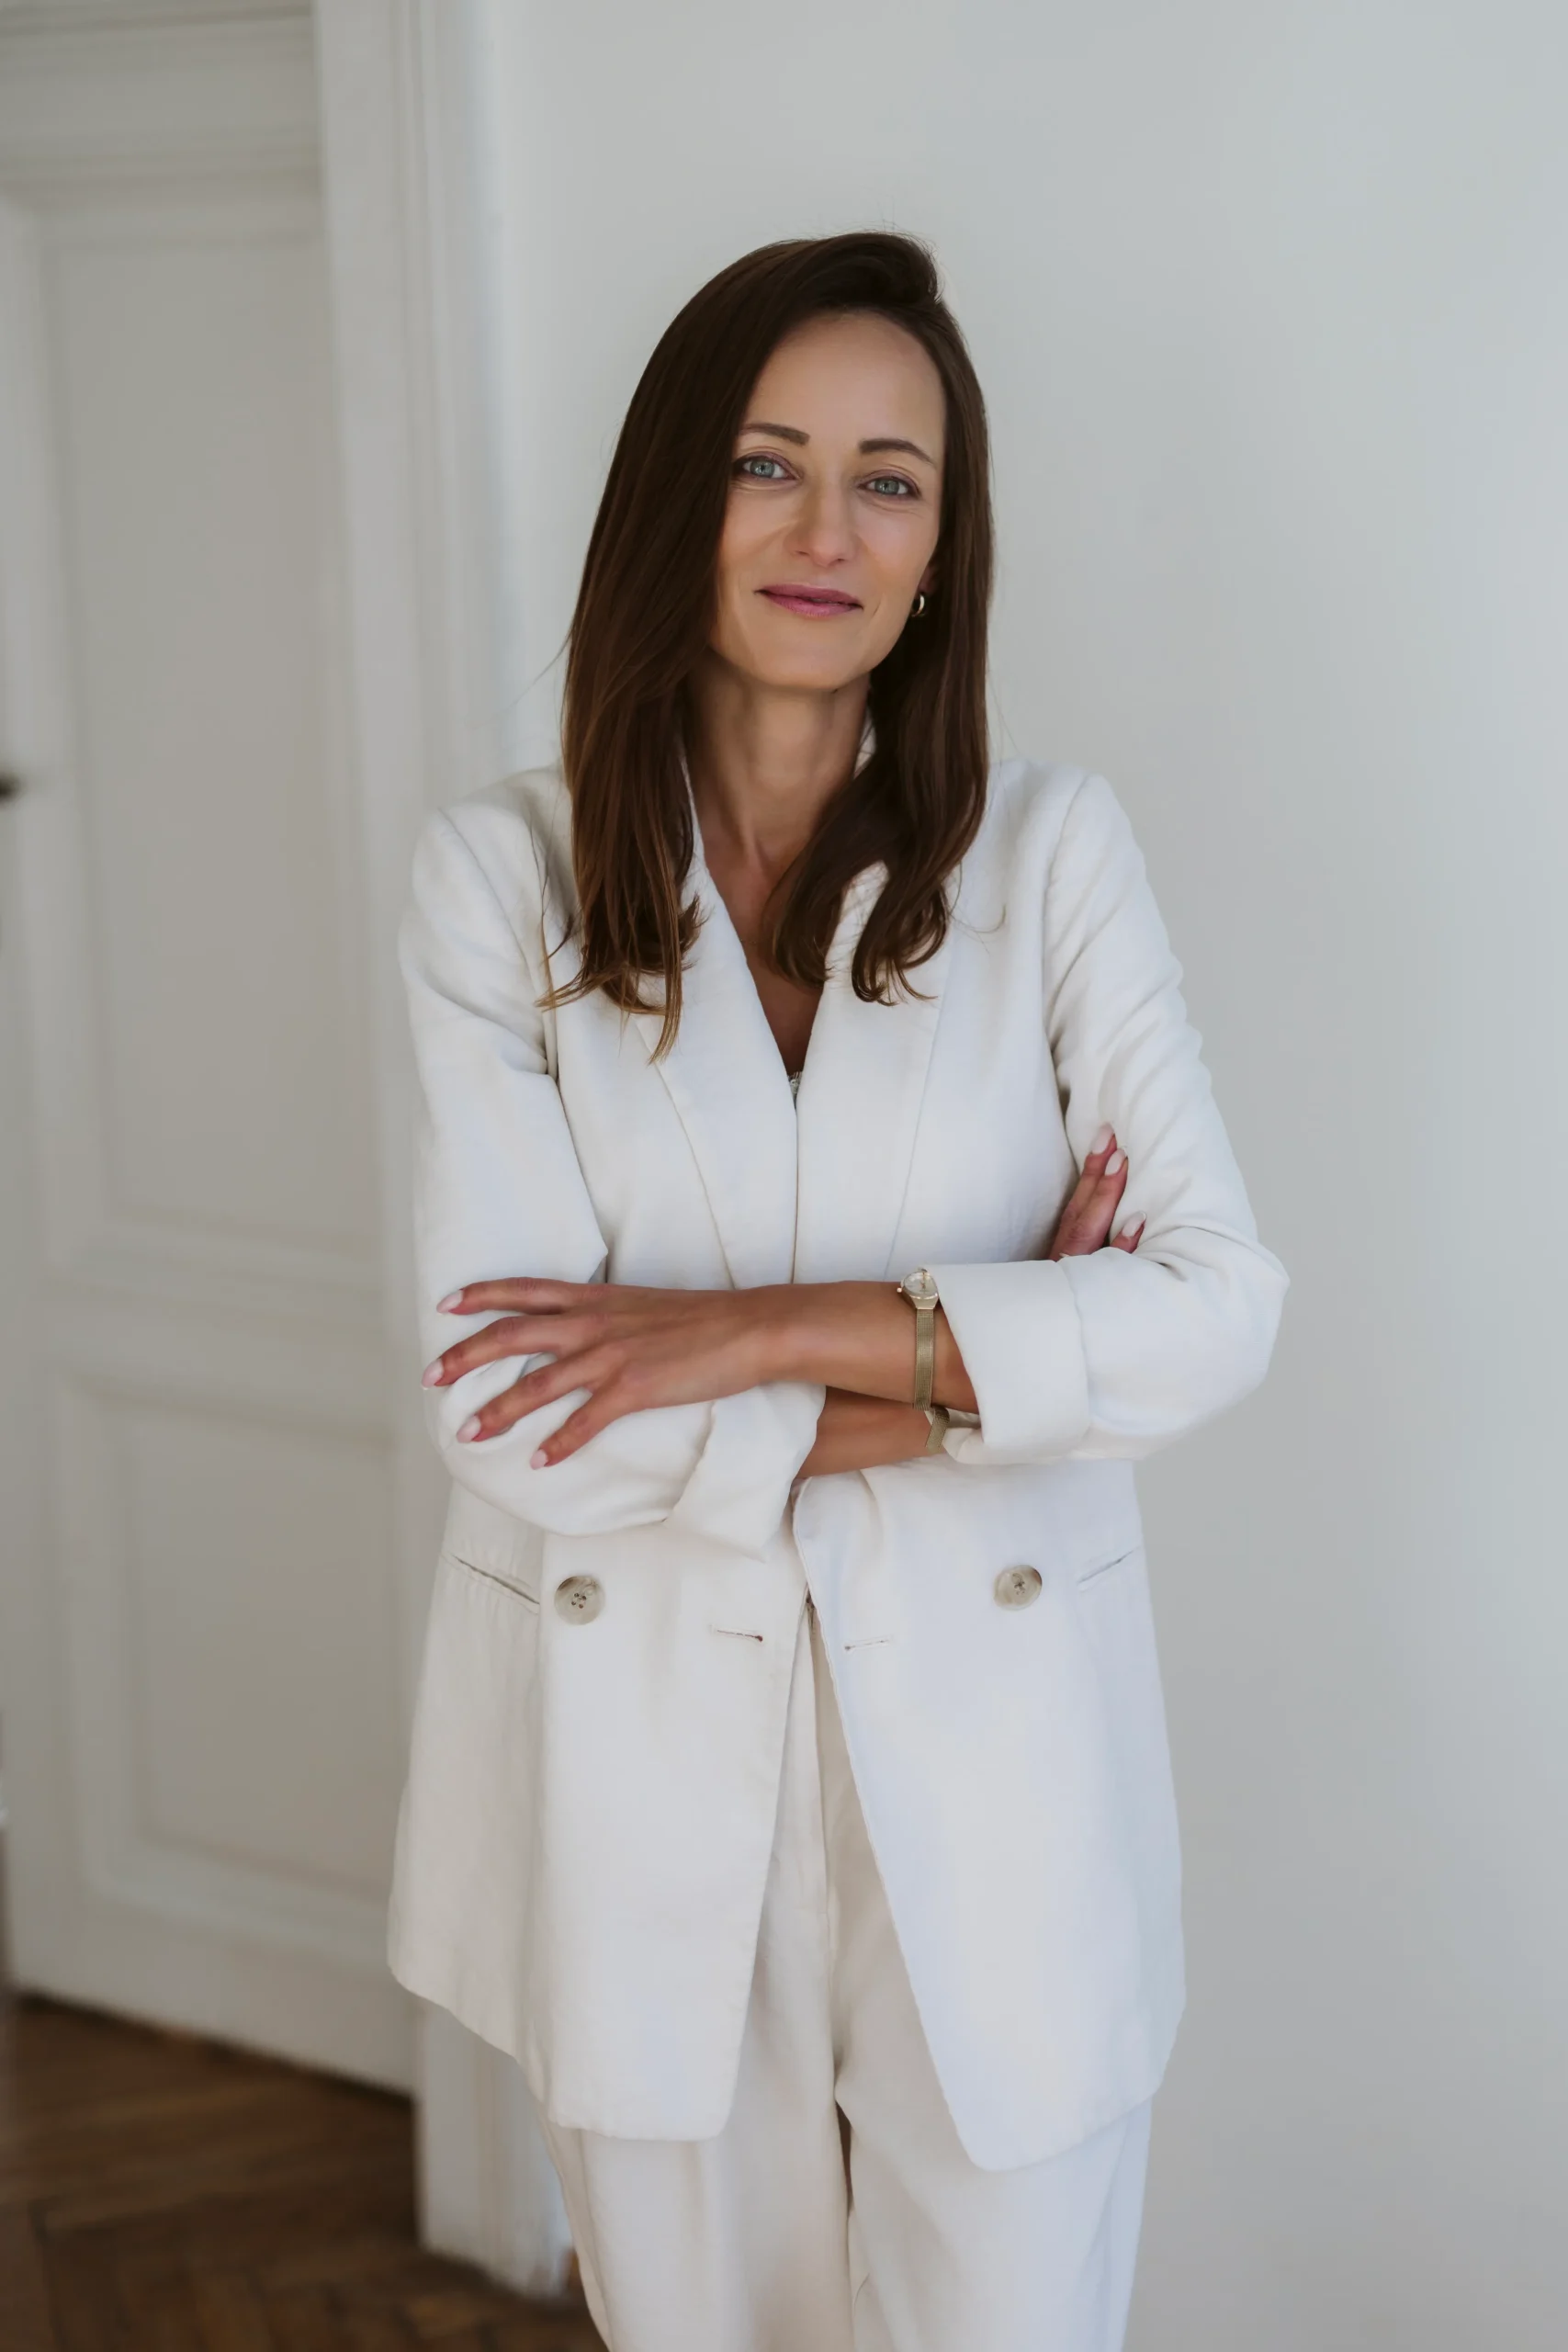
Klaudia Dzieciuch, mortgage expert in Krakow
For 18 years I have worked with mortgages. I compare bank offers, prepare and submit applications, and stay with you until the loan is paid out.
Meetings in person at Aleja Pokoju 18 in Krakow or online. I speak English and Polish.
Free analysis of your agreement
Just bring your loan agreement and the latest repayment schedule. We meet at the office at Aleja Pokoju 18 or online, and I calculate how much you can really save.