Mortgage creditworthiness: how much you can borrow
Before you start looking for a property, it is good to know how much you can borrow. I calculate your borrowing capacity at several banks and show you what raises it and what lowers it.
What is creditworthiness?
It is the highest loan amount the bank considers you can repay. The bank subtracts living costs and current instalments from your income, and from what is left it calculates the highest possible instalment. Every bank counts a little differently, so the same person can have different borrowing capacity at two banks.
What the bank counts your borrowing capacity from
Which income counts
The bank takes into account stable, documented income: where it comes from, in what form and for how long. Not every part of your pay counts in full. Bonuses, allowances and business income the bank usually averages over a longer period or reduces by costs and taxes.
Living costs and obligations
From your income the bank subtracts household living costs, instalments of other loans and limits on cards and accounts. It also adds a buffer in case interest rates rise, so your borrowing capacity comes out more cautious than today’s instalment would suggest.
Income, liabilities, BIK and loan term
| Factor | How it affects borrowing capacity |
|---|---|
| Employment contract | For the bank this is the simplest income to document. What counts is the type of contract (permanent or fixed-term), your time with the current employer and whether you are still on a probation period. |
| Business activity (B2B) | The bank usually wants a set business history and looks at income from several recent periods, not from one month. Requirements differ between banks. |
| Lump-sum tax | With a lump-sum tax the bank counts income differently than under general rules, often from revenue reduced by tax, social security and costs. Every bank does it its own way, so it is worth comparing several. |
| Credit cards and limits | The bank counts the granted limit, not just what is used. An unused card with a high limit can lower your borrowing capacity, so before applying it is worth closing it or reducing the limit. |
| Children and dependants | They raise the living costs the bank subtracts from your income, so they lower borrowing capacity. What counts is how many people are in the household. |
| BIK and repayment history | The bank checks whether current and past instalments were paid on time. Delays lower the assessment, and in extreme cases close the way to a loan. Having no credit history at all can also be a problem. |
| Loan term | The longer the term, the lower the instalment and usually the higher the borrowing capacity. But you then pay more interest, so the maximum term is not always the best choice. |
| Down payment | It does not raise borrowing capacity itself, but it decides what you can afford to buy: the price is the loan plus the down payment. A higher down payment can also give better terms, for example a lower margin. |
From analysing your capacity to choosing a property
Analysing your financial situation
I collect basic information on your income, form of employment, current liabilities and the planned purchase. You don’t need to bring documents to the first meeting.
A first calculation at several banks
I check how much you can borrow at each bank. The differences can be large, especially with your own business or several sources of income.
What to do before applying to raise your capacity
I point out what can really help: repaying small liabilities, closing unused limits, choosing the loan term or choosing the bank. I don’t promise things I have no influence over.
Choosing a property within your budget
When you know how much you can borrow, you search for apartments within a realistic budget and don’t waste time on offers the bank won’t fund.
Application, agreement and payout
I submit applications to the chosen banks and stay with you until the loan is paid out. You sign the loan agreement at the bank, and if you need or want me there, I come with you to the signing. Even later, you can contact me with questions or problems related to your mortgage. I also show you how to overpay it.
Protection in case of illness or death
A mortgage is repaid over many years. That is why I talk with every client about what happens if one of the people repaying the loan becomes seriously ill or dies. Going through the protection options is part of my job, so the loan never becomes a burden for the family.
FAQ: creditworthiness
Does a first calculation of borrowing capacity leave a trace in BIK?↓
No. A first calculation based on the information you give me is not a loan application. An enquiry in BIK appears only after the application is submitted at the bank, and before that I work out at which banks it is worth applying.
Does an unused credit card lower my creditworthiness?↓
Yes, it can. The bank usually counts the whole granted limit, not just the amount used. It is better to close an unused card or lower its limit before applying.
Can I get a mortgage on a lump-sum tax?↓
Yes, but banks count income differently on a lump-sum tax and borrowing capacity can differ a lot. That is why I compare several banks before you apply.
Do children lower my creditworthiness?↓
Yes, because they raise the living costs the bank subtracts from your income. Every bank counts them a little differently.
Does a longer loan term raise my borrowing capacity?↓
Usually yes, because the instalment is lower. But remember that with a longer term you pay more interest. I help match the term to your budget and plans.
How much does the expert’s help cost?↓
You pay nothing for my help. I am paid by the bank where the loan is taken out. The offer is the same as if you applied at the bank yourself.
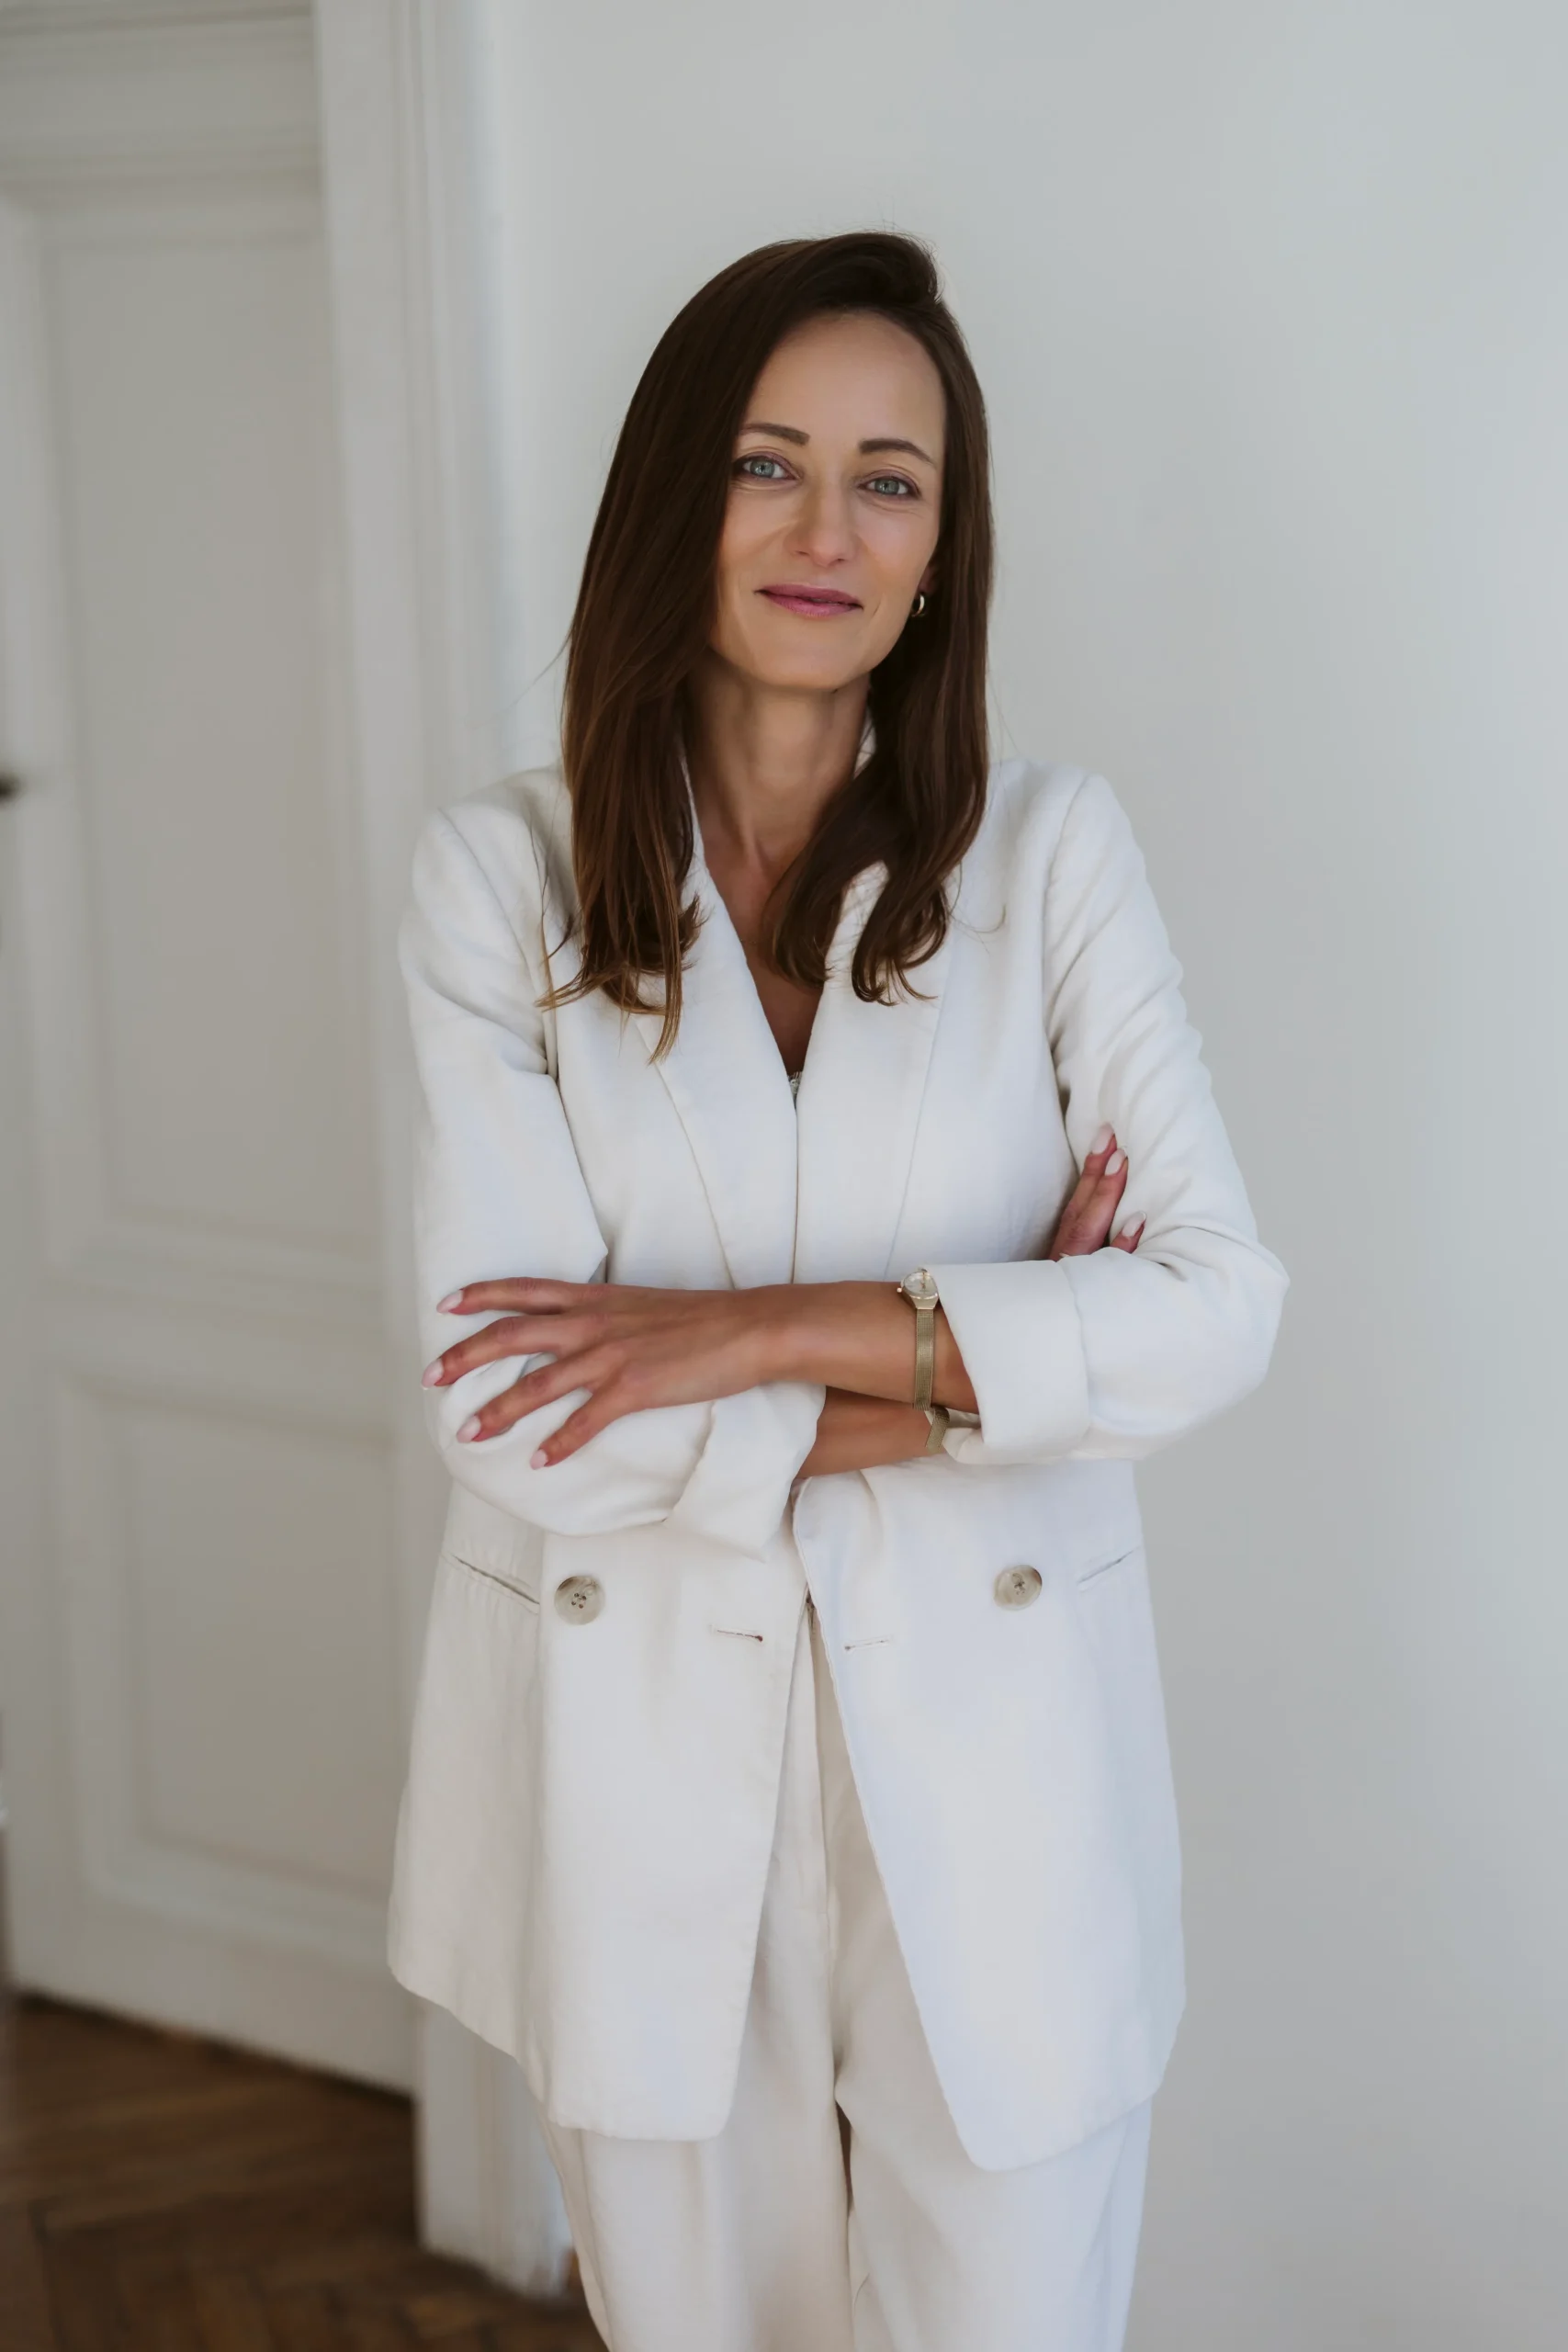
Klaudia Dzieciuch, mortgage expert in Krakow
For 18 years I have worked with mortgages. I compare bank offers, prepare and submit applications, and stay with you until the loan is paid out.
Meetings in person at Aleja Pokoju 18 in Krakow or online. I speak English and Polish.
It is worth checking your capacity before choosing an apartment
It is best to meet before you start viewing offers. Then you know right away what budget to search in. The consultation is free, in Krakow or online.