Mortgage for a secondary-market apartment in Krakow
When you buy from a private seller, well-planned deadlines matter most. I help you set them in the preliminary agreement, check the apartment’s documents from the bank’s point of view and stay with you until the loan is paid out.
How is a mortgage for a secondary-market apartment paid out?
Usually in one payment after the notarial deed is signed: to the seller’s account, and if the seller has their own loan, partly to their bank. The bank orders a valuation of the apartment and checks the land and mortgage register. The biggest risk is a deadline in the preliminary agreement that is too short, so I always plan extra time for the decision and the documents.
Three provisions to settle before you sign
Enough time for the loan
The credit decision, the valuation and the documents usually take a few weeks. A deadline for the final agreement that is too short is the most common source of problems.
Different consequences
A deposit is lost if the buyer is the one who does not complete the purchase. An advance is returned. It is worth deciding in advance what happens if the bank refuses the loan.
Down payment and loan separately
It is good to state in the preliminary agreement that part of the price comes from your own funds and part from the loan. The exact split, the account and the payment date go into the final deed.
What the bank checks for a second-hand apartment
| Document | Why it matters |
|---|---|
| Land and mortgage register | Confirms the owner and encumbrances. The most important are sections III (rights and claims) and IV (mortgages). |
| Valuation report | A valuation by an appraiser ordered by the bank. It decides how much the bank lends and how much down payment you need. |
| Certificate of no registered residents | The bank wants to be sure that the current residents will move out. |
| Certificate of no arrears in fees | From the housing cooperative or community. For a cooperative right to the unit, the cooperative also issues a certificate of that right. |
| Certificate from the seller’s bank | If the apartment is encumbered with a loan, you need the amount to be repaid and consent to delete the mortgage after repayment. |
When buying on the secondary market, the buyer usually pays 2% PCC tax. For a first apartment an exemption may apply, and its conditions are worth confirming with the notary.
From viewing the apartment to getting the keys
Borrowing capacity before you search
When you know how much you can borrow, it is easier to search and easier to negotiate the price with the seller.
Reviewing the documents and the preliminary agreement
I check the land and mortgage register and the draft agreement against the bank’s requirements and deadlines.
Applications to 2–3 banks and the valuation
I submit applications to several banks at once. I help arrange the appraiser and collect the certificates from the seller.
Loan agreement and notarial deed
I set the date for signing the agreement at the bank and match it with the notary, so that the money reaches the seller by the date in the agreement. If you need or want me there, I come with you to the signing of the loan agreement.
Mortgage entry and care after the payout
The notary (more convenient) or you can file the application for the mortgage entry. After the entry, you need to give the bank the confirmation. Even after the payout, you can contact me any time with questions or problems related to your mortgage. I also show you how to overpay it in the most cost-effective way.
Protection in case of illness or death
A mortgage is repaid over many years. That is why I talk with every client about what happens if one of the people repaying the loan becomes seriously ill or dies. Going through the protection options is part of my job, so the loan never becomes a burden for the family.
FAQ: mortgage for a secondary-market apartment
What deadline should I plan in the preliminary agreement?↓
It is better to leave a few weeks of buffer beyond the credit decision itself. You still need to collect certificates, get the valuation done and sign the loan agreement before the deed. I set the specific deadline with you once I know your situation.
Can I buy an apartment that the seller has a loan on?↓
Yes, it is a common situation. Part of your loan then goes to the seller’s bank to repay their debt, and the rest to the seller’s account. A certificate from their bank is needed.
What if the valuation is lower than the price?↓
The bank calculates the loan from the lower amount, so you have to cover the difference from your own funds. You can also negotiate the price or apply at a bank that uses another appraiser.
Does the bank finance cooperative apartments?↓
Yes, if it is a cooperative ownership right to the unit. Many banks want it to have a land and mortgage register, or for one to be created when you buy.
How much does the expert’s help cost?↓
You pay nothing for my help. I am paid by the bank where the loan is taken out. The offer is the same as if you applied at the bank yourself.
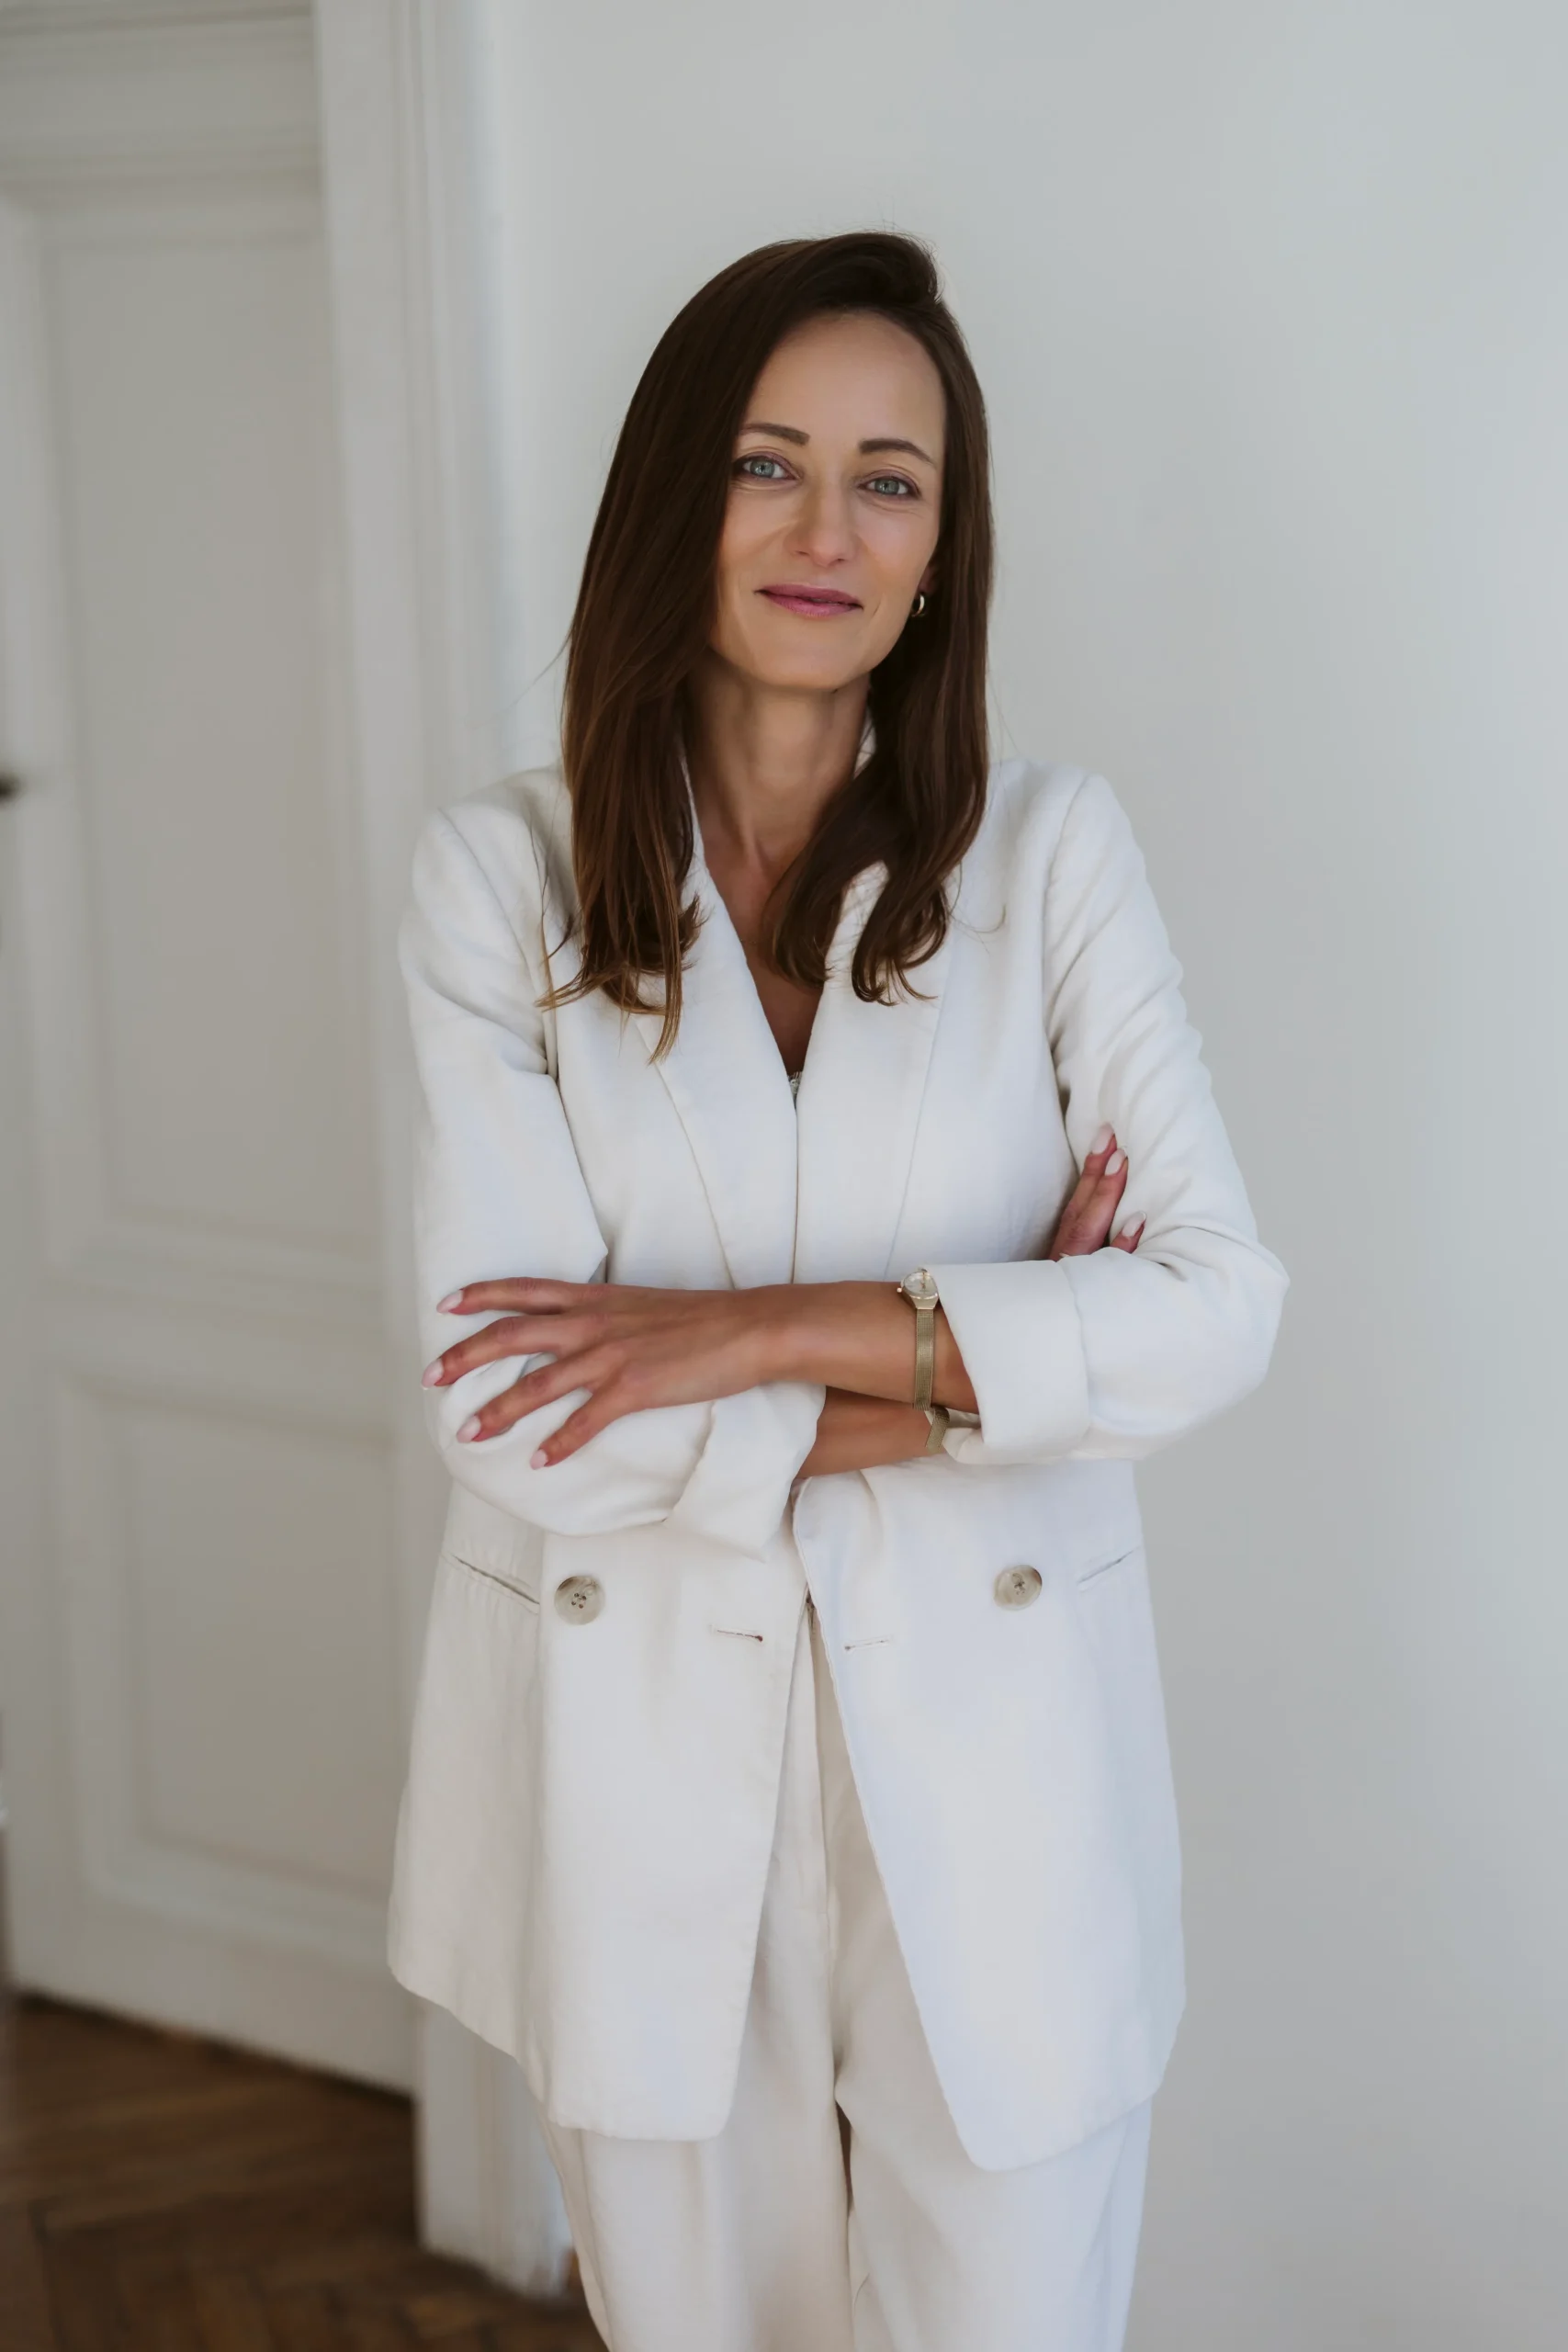
Klaudia Dzieciuch, mortgage expert in Krakow
For 18 years I have worked with mortgages. I compare bank offers, prepare and submit applications, and stay with you until the loan is paid out.
Meetings in person at Aleja Pokoju 18 in Krakow or online. I speak English and Polish.
Free consultation in Krakow or online
It is best to meet before you sign the preliminary agreement. Then the deadlines and the way of payment can be set to fit the loan.